A teacher's pension takes care of one valuable piece of retirement. It leaves a stack of decisions it doesn't make for you. Here's the difference between treating it as the finish line and treating it as the foundation.
Most financial planning advice was built around a private-sector worker with a 401(k) and no pension. For teachers, that framework leaves systematic gaps. The contractor analogy explains why — and why it isn't about quality.
The pension starts on a date. Medicare starts at 65. For teachers who retire before that birthday, there's a coverage gap that has to be funded from somewhere else — and it's often the question that catches households off guard.
Most teachers expect a lower tax bill in retirement. For households with a pension, Social Security, and years of pre-tax 403(b)/457(b) contributions, the combined picture can look different — and there's a window to do something about it.
Most teachers' investment accounts are structured as if they had no guaranteed income. Once the pension is treated as the bond-equivalent asset it actually is, the appropriate equity allocation looks very different.
Understanding the difference between investment and speculation is critical for teachers. Learn how evidence-based investing protects your long-term wealth without taking reckless market risks.
More advisors are leaving large corporate RIAs for independent firms. Here's what's driving that shift, and what it means for the person whose money is actually being managed.
Your financial priorities shift as you move from early-career educator to retiree. Explore key wealth-building strategies for every stage of your teaching career.
Your pension is the foundation of your retirement, but maximizing its value requires strategic planning. Learn how benefit formulas work and how to avoid costly payout mistakes.
From health insurance to life and disability coverage, your benefit options are complex. Get a practical breakdown of how to make the most of your district's benefits package.
Educators face unique planning traps, from underusing 403(b)/457(b) plans to miscalculating pension timelines. Here is how to spot and avoid the five biggest financial missteps.
School break rooms are frequently targeted by high-fee annuity salespeople. Learn the red flags of predatory tactics and how to ensure your advisor works as a true fiduciary.
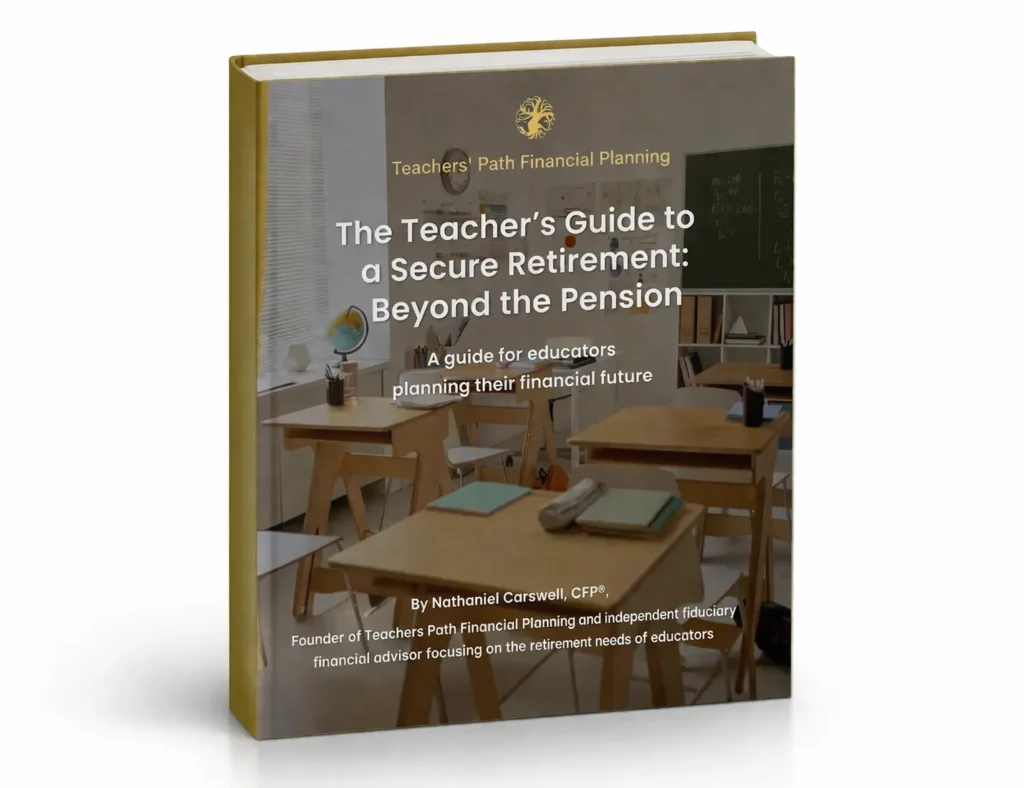
To build a truly secure and comfortable retirement, you need to look beyond the pension and consider all the pieces of your financial puzzle. Download our free e-book, “The Teacher’s Guide to a Secure Retirement: Beyond the Pension,” and start building a brighter financial future today.